A recent High Court decision, IAG New Zealand Ltd v Aubrey, is a good result for anyone relying on a contract works policy. The Court found that a common exclusion for the cost of "fixing faulty workmanship" was narrower than the insurer argued. As a result, damage caused by a contractor during the works was covered.
The case also shows that winning at the Insurance and Financial Services Ombudsman (IFSO) is not always the end of the matter.
The case
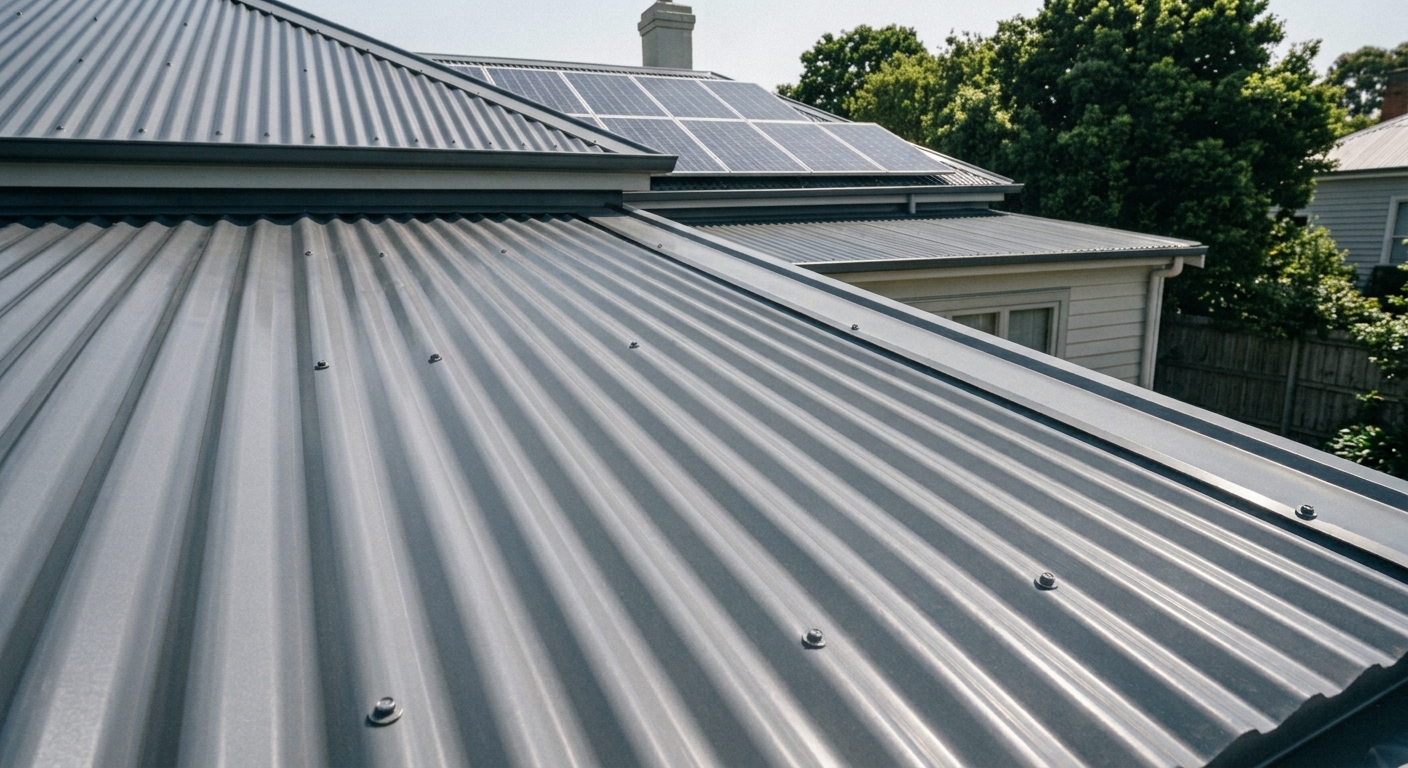
During the build of a new home in Twizel, the owners engaged a solar company to supply and install a PV system on the roof. While installing it, the solar company's workers dented several roof sheets, causing about $96,650 of damage.
The owners held a contract works policy with IAG (NZI) for the project. IAG declined the claim under the policy's faulty workmanship exclusion, which excluded the cost of "fixing faulty workmanship". That exclusion was subject to a proviso that it did not apply to resulting sudden and accidental loss to other insured property, or to other parts of the same property.
The owners took the decline to IFSO, which found in their favour. IAG did not accept that outcome and asked the High Court to rule on what the wording meant. As IFSO's rules require, IAG paid the claim in full on a without-prejudice basis and agreed to cover the owners' legal costs.
IAG argued that "workmanship" should be read broadly. It relied on an earlier Court of Appeal decision, TimTech, which described workmanship as the whole physical responsibility of performing a contract. On that view, protecting the roof sheets while working on them was part of the installer's workmanship, so the damage was excluded.
The Court disagreed. It found that the "cost of fixing faulty workmanship" is limited to the cost of redoing the work itself (here, the solar installation). It does not cover repairing physical damage caused to other parts of the property while the work was being done. The Court also noted:
- TimTech involved a liability policy, and the same meaning of "workmanship" does not automatically carry over to a contract works policy.
- It is hard to draw a line between tasks that are "integral" to a contract and those that are not.
- If insurers want to exclude this kind of damage, other, clearer wordings are available to them.
Where an exclusion is ambiguous, the courts will read it against the insurer who wrote it. The Court made no ruling on the meaning of the proviso.
Practical takeaway for builders and owners
Faulty workmanship exclusions are often used to decline contract works claims. This decision confirms that, depending on the wording, the exclusion may only remove the cost of redoing the defective work, not the damage it causes to the rest of the project. If a claim is declined on this basis, it's worth challenging.
Policy wordings differ, and insurers are likely to tighten exclusions after this decision. Check your contract works wording at renewal, particularly how it deals with damage caused by trades working on or near completed work.
Note: An IFSO ruling in your favour can still be taken to court by the insurer. If that happens, the insurer must pay your claim and your legal costs while the court decides. If you've had a claim declined, talk to us before accepting the decision.